|
Financial support for rural communities has been a feature of US economic policy since the Farm Credit System was established as the first GSE in 1916[1], sixteen years before the Federal Home Loan Banks were established in 1932[2]. This support continues to this day and has expanded to encompass additional programs. Ginnie Mae Program While the best-known collateral for Ginnie Mae securities is loans underwritten through the FHA and VA programs, another form is loans underwritten by the US Department of Agriculture Rural Development (RD) Program, launched in 1990 as part of the Farm Bill passed that year[3]. The Single-Family Direct Home Loan Program[4] in particular is designed to provide payment assistance to low- and very-low-income households in rural communities. Of course, FHA and VA provide loans in rural areas under the terms of their programs as well. GSE Rural Lending Single-family lending at Fannie Mae and Freddie Mac was handed a mandate to provide liquidity to rural communities through the adoption of the Duty-to-Serve provision of the HERA Act enacted in 2008[5]. This program requires the GSE’s to engage in activities to facilitate liquidity in three underserved markets:
A key feature of this regulation is that FHFA has provided new datasets and tools to enhance the analysis of these markets[6]. In particular, Rural Areas FHFA's Duty to Serve regulation defines "rural area" as: (1) a census tract outside of a metropolitan statistical area, as designated by the Office of Management and Budget; or (2) a census tract in a metropolitan statistical area, as designated by the Office of Management and Budget, that is outside of the metropolitan statistical area's Urbanized Areas as designated by the U.S. Department of Agriculture's Rural-Urban Commuting Area Code #1, and outside of tracts with a housing density of over 64 housing units per square mile for USDA's RUCA Code #2. Below is a link to the specific geographies which meet the Rural Areas definition. Using this segmentation, we are now in a position to load their definition into our databases and look at trends in this market segment. Using HMDA data as a base, we produce the following chart[7]: 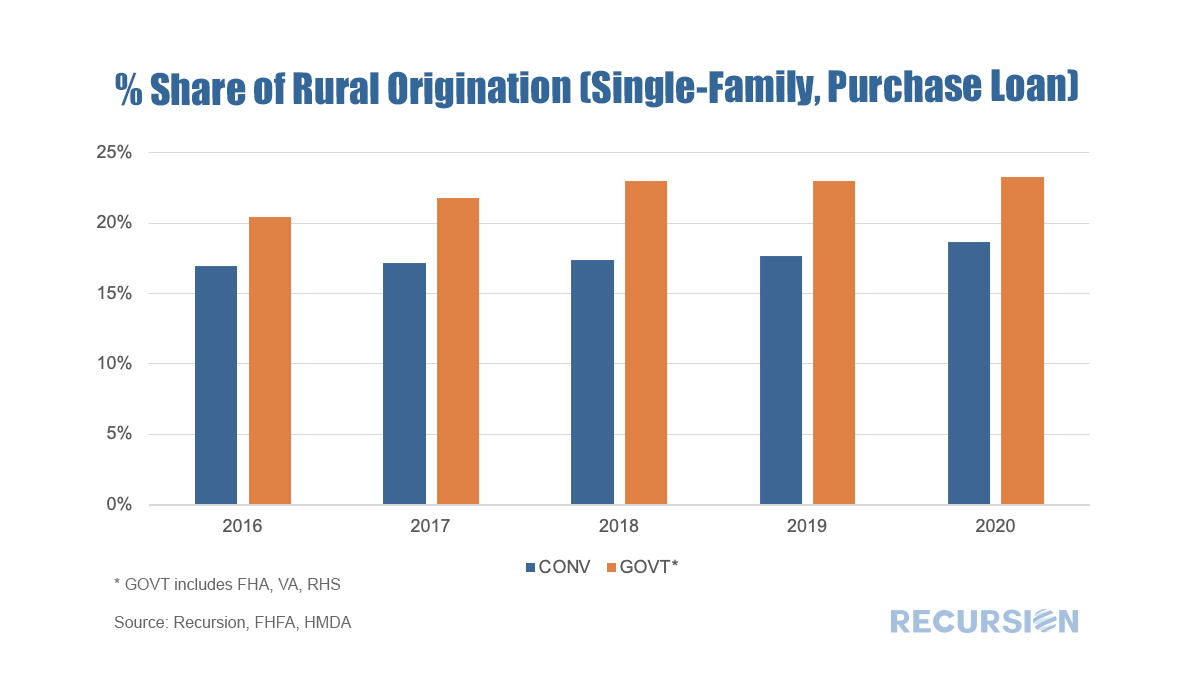 As we have commented several times, the Federal Reserve Z.1 data is a fine source of information on long-term financial market trends. This post looks at trends in ownership of single-family mortgage risk. The chart below shows this distribution from Q1 2007 to Q3 2020: 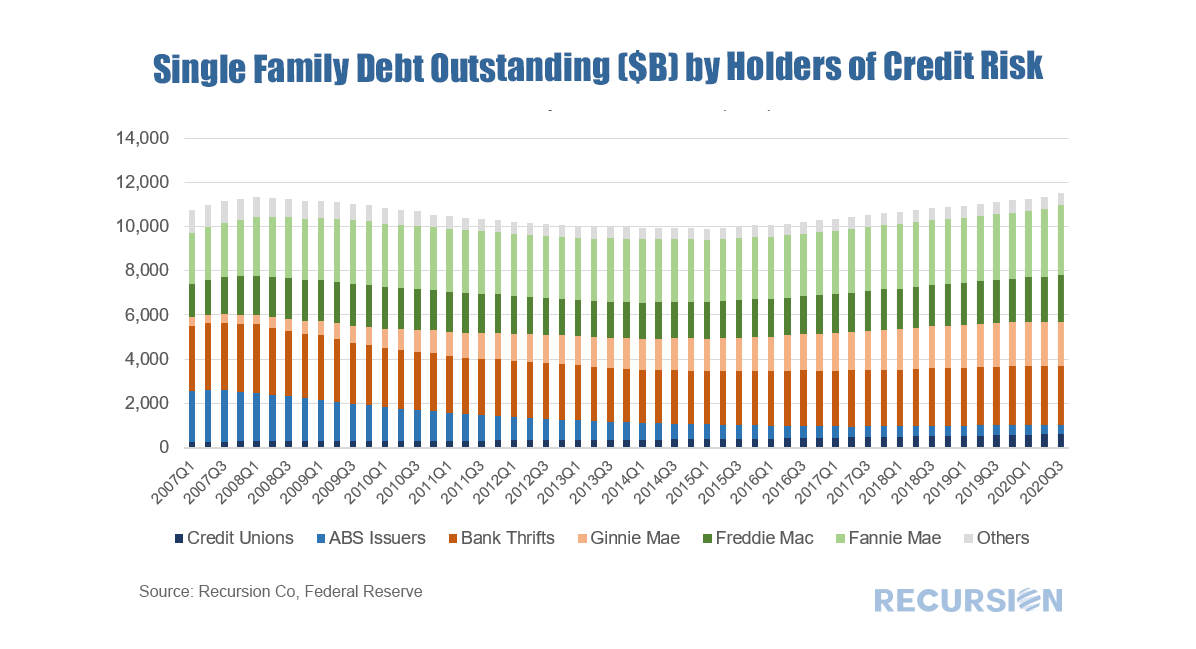 While the single-family housing market is booming, the trend in the multifamily market is much more nuanced. Over the 3 ½ year period from July 2017 to December 2020, new supply as measured by housing starts was in a steady-to-modestly rising trend. This changed with the onset of the Covid-19 pandemic: 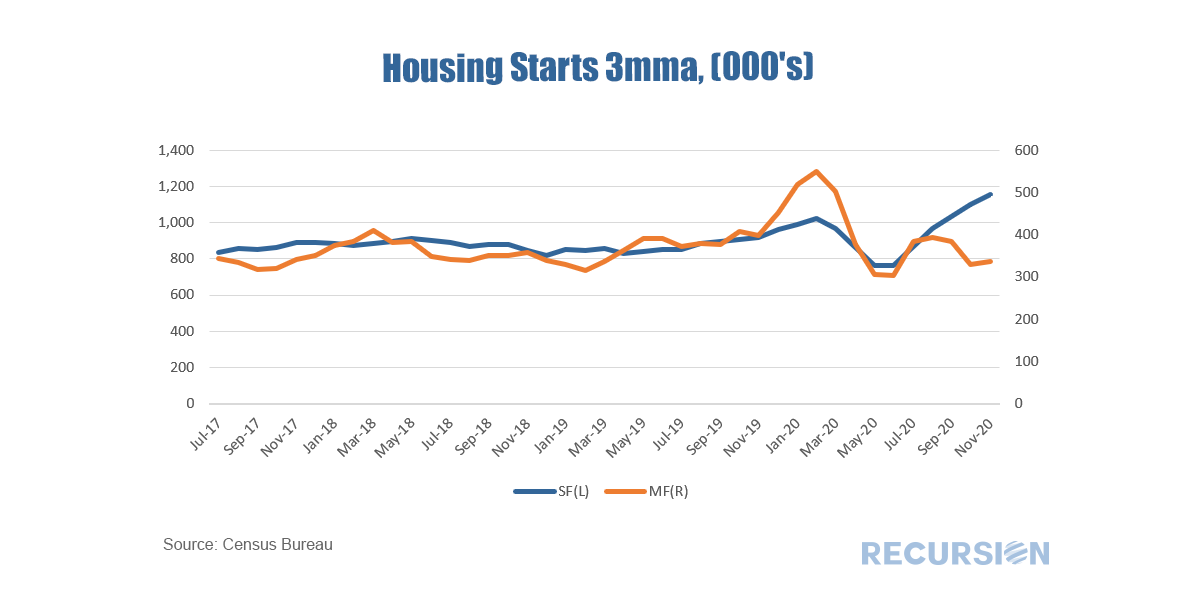 Overview
With the onset of the Covid-19 crisis, the role of the banking sector has once again risen to the forefront of concern. As noted in an earlier post[1] the sharp spike in unemployment is certain to lead to a surge in delinquencies. Substantial purchases by the Federal Reserve of Mortgage Backed Securities (MBS) have had a limited impact on rates facing borrowers[2] due in part to uncertainty around the magnitude of the losses and who will bear the costs. Policies regarding forbearance and liquidity provision to mortgage servicers are having an impact on lending standards and the availability of credit. Banks play a significant role in the mortgage pipeline as originator, servicer and investor. Most of the current focus is on the first two, but the importance of their role as investor is also crucial. According to Home Mortgage Disclosure Act (HMDA) data Recursion uploaded to the cloud, 3.1 million individual single family loans with a balance of $739.4 billion were originated in 2018 by the banks, of which 60.4% were held on their balance sheet. Each loan file in the data set contains many characteristics, including originator information. As banks originated about 43% of all mortgages that year, the implication is that about one quarter or all residential mortgage production was kept by the banks. |
Archives
August 2026
Tags
All
|
 RSS Feed
RECURSION |
|
Copyright © 2024 Recursion, Co. All rights reserved.